Truist Mobile

Screenshots
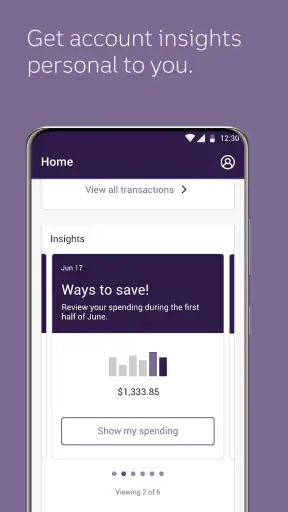
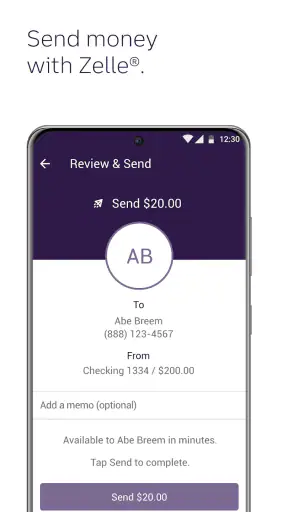
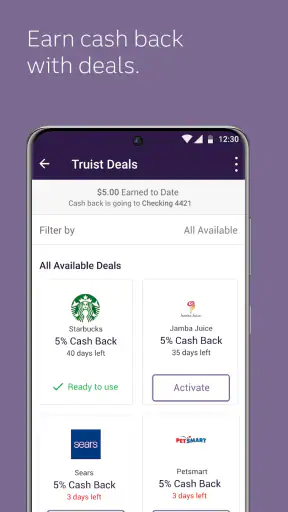
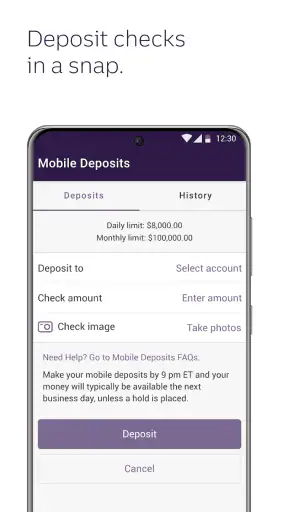
Details
- Rating
- 39.64K reviews
- Version
- Varies with device
- Developer
- Truist Financial Corporation
Analysis by Norviv
Choosing a mobile banking app is less about finding the most colorful interface and more about finding one that fits the way you actually handle money. I look for quick access to everyday account information, a sensible path through common tasks, clear security habits, and enough detail to make decisions without opening a laptop. Truist Mobile is built for customers of Truist Financial Corporation, so its biggest advantage is not that it tries to be a universal finance tool. Its value comes from putting Truist banking in a phone-friendly format.
I reviewed it as a finance app rather than as a general budgeting service. That distinction matters. A bank’s own app can be the most convenient place to check an account, move money, and keep an eye on activity, while a separate budgeting app may be better for combining accounts from several institutions. If you already use Truist, the practical question is whether the mobile experience makes routine banking easier. If you do not, the decision is really about whether changing your primary bank is worth the disruption.
What I considered before recommending Truist Mobile
I considered the recommendation through the lens of repeated use, not just the first convenient balance check. The key question for me is whether a banking app supports a small, dependable routine without encouraging unnecessary monitoring or making ordinary account checks feel like work. That perspective also helps separate the value of mobile access from the larger decision of choosing a bank.
The first test is everyday banking, not impressive extras
When I assess a banking app, I start with the tasks I might need during an ordinary week: checking whether a payment has cleared, reviewing recent activity, confirming a balance before making a purchase, and dealing with a transfer without searching through a desktop website. Those actions should feel direct. A finance app becomes frustrating when it makes simple questions feel like a research project.
Truist Mobile is free and has an Everyone content rating, which makes it approachable for a broad range of account holders. It was released on April 27, 2021, and supports Android devices running version 9 or later. That minimum operating-system requirement is worth checking before installing, especially if you keep an older phone for banking or use a device that no longer receives regular updates.
I also pay attention to whether an app suits a particular banking relationship. This is not a standalone wallet designed to replace a bank account, nor is it a neutral dashboard for every financial provider. It is the mobile channel for Truist customers. That focus can make the experience more coherent than juggling a bank website, a separate mobile browser, and unrelated tools, but it also means the app is a poor fit if your accounts are elsewhere and you only want a general money-management screen.
Account visibility is useful only when it supports decisions
A balance by itself is not enough. I want to understand what has recently happened, which transactions are pending, and whether an unexpected change deserves attention. In practice, that means using the app as a quick checkpoint rather than treating the main balance as the whole financial picture. Before paying a large bill, for example, I would review recent activity instead of relying on memory about a transaction from a few days earlier.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
That habit is especially helpful for people who use a debit account for many small purchases. A quick review can reveal whether a purchase is still being processed or whether several routine charges have already reduced the amount available. The app is most valuable in these short, repeated visits: open it, verify the situation, take the next action, and close it.
There is also a useful trade-off here. A bank app generally has the most direct view of that bank’s own relationship, while a third-party finance app may offer a wider household overview. I would choose Truist Mobile for first-party account control and a separate tool only when my main need is seeing accounts across multiple institutions in one place.
Security is a workflow, not just a label
Banking on a phone requires a little discipline from the user. I would install the app only from the official Android or iOS store, keep the phone’s operating system current, and avoid handling sensitive account activity on a device that other people regularly unlock. I would also review every sign-in or confirmation prompt carefully rather than approving something automatically.
The important point is that a banking app cannot compensate for careless phone habits. A strong passcode, a protected device, and attention to unexpected messages matter just as much as the app itself. When I use a finance app, I prefer short sessions: check what I need, complete the task, and sign out or lock the device rather than leaving the account open on a shared screen.
For a household that shares financial responsibilities, this can become a practical question. One person may want convenient mobile access, while another may prefer a desktop browser or in-person support. I would not make the app the sole reason for choosing a bank. I would treat it as one part of the service, then decide whether the overall banking relationship meets my needs.
How the app compares with the usual alternatives
The closest alternative is usually a bank’s mobile app from another institution. Those apps compete on the same basic promise: account access wherever you are. In that comparison, the decisive factor is often not a dramatic feature difference but the quality of the underlying bank relationship, the accounts you hold, and how often you need help outside the app.
A second alternative is a mobile browser. A website can be useful when you are on a computer or need a larger screen, but a dedicated app is more natural for a quick balance check while away from home. I would favor the app for frequent short interactions and the browser for situations where I need more space to inspect several pieces of information at once.
The third category is an independent budgeting or account-aggregation service. That option may be better for someone who wants spending analysis across several banks, cards, or financial products. Truist Mobile is the more sensible choice when the task begins and ends with Truist. The two categories are not necessarily rivals; some people will reasonably use both, with the bank app handling direct account activity and the broader tool helping with planning.
Where Truist Mobile is strongest—and where the trade-offs appear
The strongest case is focused access to a Truist relationship, while the main trade-offs emerge when someone needs a multi-bank view or rarely banks by phone. I’ll weigh those differences in practical terms: how much ongoing attention the app asks of you, what habits make it more useful, and when a browser or broader finance tool is likely to serve you better.
Its strongest point is the focused banking relationship
What I like most about Truist Mobile is the clarity of its purpose. I am not opening it to browse financial articles, compare products from unrelated providers, or build a complete household balance sheet. I am opening it because I bank with Truist and want a mobile route into that relationship. That focus is easier to understand than an app that tries to be a bank, a budgeting coach, and a financial marketplace at the same time.
The app also has a substantial user base: it has more than one million installs, an average rating of 4.8, and roughly 382 thousand ratings. Those figures do not guarantee that every person will enjoy the same experience, but they do suggest that mobile access is an established part of how many Truist customers interact with the bank.
For me, the most convincing use case is a quick decision at an inconvenient moment. Imagine standing at a checkout and wondering whether a recent bill has already reduced the account balance. Instead of waiting until you reach a computer, I would open the app, review the latest activity, and decide whether to continue. That is a small interaction, but it is exactly where mobile banking earns its place.
A useful workflow: check, verify, then act
I recommend separating observation from action. First, check the balance and recent activity. Second, verify that the account and transaction details match what you expect. Only then should you proceed with a transfer, payment, or other financial task. This extra pause is easy to skip when an app feels convenient, but it reduces the chance of acting from an outdated assumption.
Another practical habit is to use the app after important financial events rather than only before them. After making a significant payment or moving money, I would return later to confirm how the activity appears. That creates a simple personal record and helps distinguish a completed transaction from one that is still being processed. It is a better routine than checking only when the balance looks surprising.
I would also avoid using a banking app as a substitute for a spending plan. Seeing transactions is not the same as deciding how much to save, setting a household budget, or comparing long-term goals. Truist Mobile can support those decisions by giving me current account information, but I would still use a separate method—a spreadsheet, notes, or a dedicated planning service—if I needed detailed analysis.
Why some users may prefer another category
The main limitation is the same thing that gives the app its focus: it centers on Truist. Someone with accounts spread across several banks may find repeated sign-ins and separate balances inconvenient. In that situation, an aggregation or budgeting service may provide a better overview, even if direct banking actions still need to happen inside each institution’s own app.
I would also hesitate to recommend it to a person who rarely uses a smartphone for financial tasks. If you prefer visiting a branch, calling support, or using a full desktop setup, installing a mobile app may not change your experience enough to justify learning another interface. The app is most useful when mobile access is genuinely part of your routine.
There is a similar trade-off for people who want extensive financial education or investment analysis in one place. A focused bank app may feel refreshingly uncluttered, but it will not necessarily replace specialized tools for portfolio research, credit monitoring, tax organization, or detailed spending analytics. I would choose the narrower tool when I value directness and add other tools only for a clearly defined need.
The cost of switching deserves more attention than the download
Because the app itself is free, the real cost is not the installation. The bigger commitment is changing where your money is held if you are not already a Truist customer. Moving direct deposits, recurring payments, saved payment details, and emergency funds can take time. I would not switch banks simply because an app looks convenient in a store listing.
If I were considering Truist, I would first write down every automatic financial connection attached to my current account. That includes regular bills, subscriptions, employer payments, transfers, and any service that uses the old account for verification. I would then decide whether the broader banking relationship—not just the phone experience—offers a meaningful reason to move.
For an existing Truist customer, the switching cost is much lower. The decision is mainly whether to add the mobile channel to an account relationship already in place. In that case, I would install it on my personal device, confirm that the operating system meets the requirement, and begin with low-risk tasks such as checking activity before relying on it for more important actions.
One non-obvious trade-off is convenience versus attention. Mobile access makes it easy to check an account almost anywhere, but that can encourage anxious, repetitive checking without improving financial decisions. I get more value when I use the app at specific moments—before a large purchase, after a scheduled payment, or during a weekly review—rather than opening it every time I feel uncertain.
Who should choose it
I would recommend Truist Mobile most strongly to an existing Truist customer who wants a straightforward way to stay connected to the bank from an Android or iOS device. It makes sense for people who check balances away from home, review recent activity regularly, and prefer a dedicated app over navigating a mobile browser.
It is also a reasonable choice for someone who wants first-party access rather than linking bank details to a separate financial dashboard. That does not make it automatically better for every purpose, but it keeps the main banking relationship in one place. The app’s Everyone rating also makes it broadly approachable, although each household should still decide who should have access to the device and account.
I would skip it as a primary solution if my goal were a complete multi-bank budgeting system, a specialized investing workspace, or a replacement for every financial service I use. In those cases, I would use a tool designed around the broader job and keep a bank-specific app for direct account access.
My recommendation after weighing the alternatives
My final view is positive but specific: Truist Mobile is a practical choice for Truist customers who want banking access that fits short, everyday phone sessions. Its free price, established adoption, and focused purpose make it easy to justify when the underlying bank relationship is already yours.
I would not choose a bank solely because its mobile app has a strong rating. A rating of 4.8 from around 382 thousand ratings is encouraging, yet personal fit still matters more than popularity. Before deciding, I would ask whether I need one-bank access or a multi-bank overview, whether I prefer mobile or desktop banking, and whether switching institutions would solve a real problem rather than create administrative work.
For the right user, the best approach is simple: install it on a supported device, protect the phone, learn the path to recent activity, and build a habit of verifying important transactions after they happen. That workflow turns the app from a passive balance viewer into a useful checkpoint for daily money decisions.
My recommendation: choose it if you already bank with Truist and want a convenient mobile companion; consider a broader finance tool alongside it if your money is spread across institutions. If you are not a Truist customer, compare the complete banking service first and treat the app as an important convenience, not the whole decision.
Frequently Asked Questions
01What is Truist Mobile, and what can I do with the app?
Truist Mobile is the official mobile banking app for Truist customers. After signing in, you can typically check account balances and transaction history, transfer money, deposit eligible checks, pay bills, manage debit and credit cards, locate branches or ATMs, and review certain account details. Available features may depend on your account type, location, device, and Truist’s current service availability.
02Is Truist Mobile safe to use for banking and payments?
Truist Mobile uses security measures designed to protect your banking information, such as encrypted connections, secure login procedures, fraud monitoring, and optional biometric authentication on compatible devices. However, no banking app eliminates every risk. Download it only from the official Google Play Store or Apple App Store, keep your phone updated, avoid public Wi-Fi for sensitive activity, and never share your password or verification codes.
03Can I deposit checks and transfer money using Truist Mobile?
Yes, eligible customers can generally use Truist Mobile for mobile check deposits and transfers between qualifying accounts. Check deposits usually require photographing the front and back of the endorsed check, while transfers may require you to select accounts, enter an amount, and confirm the transaction. Deposit limits, processing times, transfer availability, and eligibility can vary, so review the app’s instructions before submitting anything.
04Does Truist Mobile charge fees for using its features?
Downloading and using the Truist Mobile app itself is generally not a separate subscription service, but standard account terms and transaction fees may still apply. Possible charges can depend on your checking or savings account, overdraft activity, wire transfers, expedited services, mobile carrier data usage, or other banking actions. Check Truist’s current fee schedule and your account agreement before relying on a specific feature.
05What should I do if Truist Mobile will not open or I cannot sign in?
If Truist Mobile fails to open, freezes, or rejects your login, first check your internet connection and confirm that the app and operating system are updated. Restarting the device or reinstalling the official app may also help. Do not repeatedly enter uncertain credentials, and never use links from suspicious messages. If the problem continues, contact Truist through an official website, phone number, branch, or in-app support option.


